
Key Points
- Borrowers who expected forgiveness or another pause extension reduced their loan payments by $40 per month on average.
- Those same borrowers are 7.5% more likely to be seriously delinquent today.
- Betting on relief that never arrived can cost up to 43% of a borrower’s original loan balance.
Borrowers who believed the student loan payment pause would keep getting extended (or that their debt would be forgiven outright) cut their payments, spent more, and are now more likely to be delinquent, according to a new National Bureau of Economic Research working paper.
Economists surveyed borrowers about their expectations during the pause and the 2022 forgiveness announcement, then linked those responses to credit bureau, employment, and spending data.
The key finding: policy uncertainty itself changed borrower behavior, and the costs are still showing up in student loan debt statistics today.
Would you like to save this?
Why It Matters
Between March 2020 and 2023, the payment pause was extended eight times, often at the last minute after being framed as “final.” President Biden’s August 2022 mass forgiveness plan was announced, litigated, and struck down by the Supreme Court in June 2023, but borrowers had already adjusted their finances as if relief was coming.
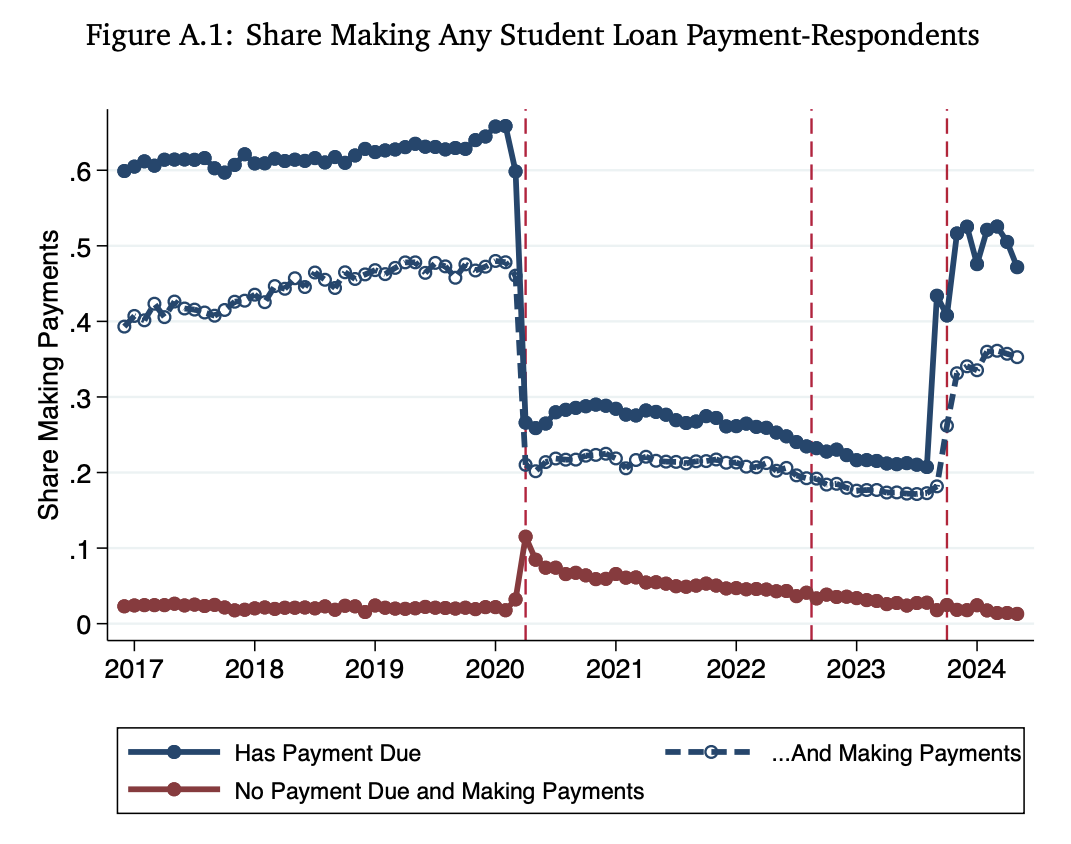
The study puts hard numbers on what that whiplash cost. Borrowers who bet on relief that never arrived paid more interest, fell behind more often, and in some cases are thousands of dollars worse off. You can see in the chart below how many borrowers were making payments over almost the last decade:
By The Numbers
Borrowers who were optimistic about loan forgiveness reduced their student loan payments by $40 per month and increased spending on non-durable goods by $100 per month, even as payments were set to restart.
Borrowers who expected another pause extension also cut payments by $40 per month and were 7.5% more likely to be at least three months delinquent by May 2025, well after payments resumed.
The study’s authors found that losses from incorrect beliefs about forgiveness can exceed 43% of a borrower’s initial loan balance.
The American Enterprise Institute notes that reduced payments made in anticipation of forgiveness cost borrowers up to 7% of their balances in added interest, which equates to thousands of dollars on a typical loan balance.
What The 43% Loss Figure Really Means For Borrowers
That 43% figure doesn’t mean loan balances grew 43% (though balances did grow).
Here’s the simple version: imagine you owe $100, and someone in charge keeps hinting the debt might be erased. So you stop paying and spend the money elsewhere. Three costs pile up while you wait:
- Your debt keeps growing due to interest, so the $100 balance increases.
- When the forgiveness never comes, you’re out of the habit of repayment and more likely to miss payments, bringing late-payment damage like a wrecked credit score (which is separately very costly).
- The money you spent while waiting went to choices you wouldn’t have made if you’d known the truth.
The economists added up all of that harm (what they call a “welfare loss”) and compared it to the original loan. For the borrowers who bet hardest on forgiveness that never came, the total damage can be worth more than 43% of the starting balance. It’s a worst-case estimate, not the average borrower’s experience.
If you want to focus just on extra interest accumulated, that cost is the “up to 7%” figure. That’s similar to the estimates of $3,500 in extra interest costs for those who’ve been staying in the SAVE forbearance.
The Bigger Picture
“When policymakers announce policies that later face legal or political obstacles, households may adjust their spending, saving, borrowing, and repayment decisions in anticipation of benefits that may never arrive.” the study’s authors write.
That pattern hasn’t gone away. The Department of Education partially resumed involuntary collections in 2025 (including wage garnishment and tax refund offsets) then abruptly halted them again in January 2026 with no firm timeline for restarting.
Borrowers sitting in default while collections are on hold continue to accrue interest and fees, meaning balances will be larger whenever enforcement returns.
How This Connects
The study helps explain the delinquency wave we’ve been tracking. Education Secretary Linda McMahon told senators that roughly 1 in 4 federal student loan borrowers are now delinquent or in default, and New York Fed data showed 3.6 million borrowers newly in default, with credit scores dropping an average of 91 points. Defaulted loan balances have reached $179 billion and are now set to be collected by a downsized Treasury.
The research suggests these numbers aren’t just about borrowers who can’t pay. Years of stop-and-start policy taught many borrowers to expect that payments were optional or forgiveness was imminent and rebuilding repayment habits is proving slow and expensive. For borrowers already in default, options like loan rehabilitation can stop the damage from getting worse.
The paper’s warning applies to the current administration as much as the last one: every open-ended pause or vague “we’ll resume collections eventually” signal shapes borrower behavior now.
The Education Department has already told borrowers to expect repayment, not forgiveness — the study suggests clear timelines and credible commitments cost less, for the government and for borrowers, than relief that may never arrive.
Don’t Miss These Other Stories:
10 Best Private Student Loan Lenders For College
Best Student Loans And Current Rates In July 2026
$5,250 of Employer Student Loan Assistance Is Tax-Free
Editor: Colin Graves
The post Waiting On Biden’s Student Loan Forgiveness Cost Borrowers Up To 43%, NBER Finds appeared first on The College Investor.

