
The Student Aid Index (SAI) is the key metric that colleges use to calculate your financial need as a relates to providing financial aid packages.
The Student Aid Index (SAI) replaced the Expected Family Contribution (EFC) when calculating financial aid needs for families paying for college. This is the key formula that can help unlock scholarships, grants, federal student loans and other financial aid.
Both are calculated through formulas with information derived from the FAFSA form. The big reason behind the change is to create a better reflection on the true cost of colleges.
The formula is simple: cost of attendance (COA) minus Student Aid Index (SAI) and other financial assistance equals eligibility for need-based financial aid. But it’s never simple…
In the past, many families have interpreted the EFC as the total cost that they will be expected to pay. However, many face higher costs because colleges don’t meet the full need of students or include loans as a part of the financial aid package.
The new term, Student Aid Index, can’t erase the feelings that parents face when confronted with the costs of higher education. But it may allow parents and students paying for college to approach the financial challenge with fewer perceived expectations. With a more general term, parents may not feel solely responsible for funding their child’s higher education.
Would you like to save this?
Student Aid Index Chart (Formerly EFC Chart)
For the majority of families thinking about how to pay for college for the first time, the SAI Chart is probably going to be pretty shocking. Remember, a “good SAI” is lower – the lower the score, the higher the potential for need-based financial aid.
Keep in mind this SAI Chart (EFC Chart) is only an estimate, and at some point you’re going to want to put in your real data. See the SAI calculator below the chart to enter your data.
When you check out the SAI Chart below, keep in mind that these figures are estimates and may change. Furthermore, assets are assumed to be zero, and student income is assumed to be zero.
Negative SAI are left at zero since zero and below are treated equally.
You can find your family adjusted gross income (AGI) on the left, see how many dependent children you have, and you can see your Student Aid Index in the chart. The higher the SAI number, the less student aid you’ll be eligible for.
How To Read The Chart:
The chart is simply an estimate for whether or not you’ll receive financial aid based on your SAI number. Your AGI and number of dependents give an estimated SAI based on $0 assets. If you have assets, you’ll have a higher SAI. Then use the color codes below to get a sense of your aid eligibility:
- Green: Eligible for need-based aid at Public 2-Year, Public 4-Year, Private 4-Year, Elite Colleges
- Yellow: Eligible for need-based aid at Public 4-Year, Private 4-Year, Elite Colleges
- Orange: Eligible for need-based aid at Private 4-Year, Elite Colleges
- Red: Eligible for need-based aid at Elite Colleges
- Purple: No Need-Based Aid Eligibility
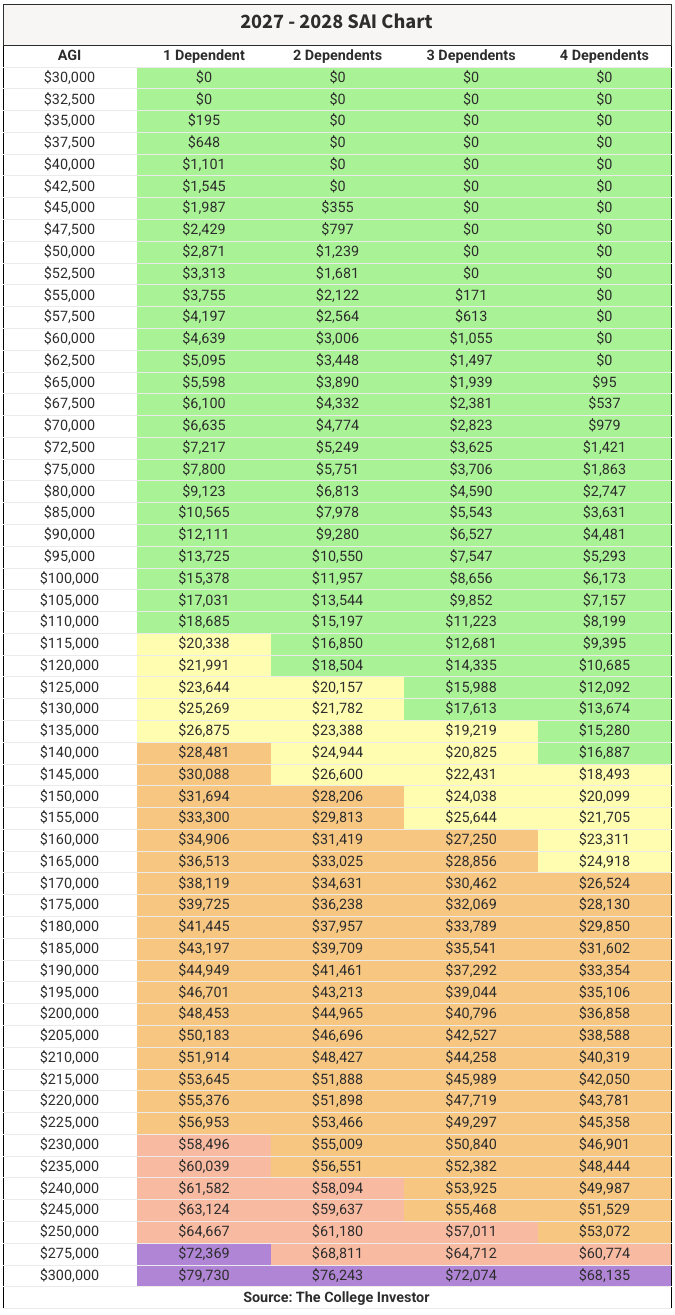
Here is an HTML version of the SAI Chart:
2027 – 2028 SAI Chart |
||||
|---|---|---|---|---|
|
AGI |
1 Dependent |
2 Dependents |
3 Dependents |
4 Dependents |
|
$30,000 |
$0 |
$0 |
$0 |
$0 |
|
$32,500 |
$0 |
$0 |
$0 |
$0 |
|
$35,000 |
$195 |
$0 |
$0 |
$0 |
|
$37,500 |
$648 |
$0 |
$0 |
$0 |
|
$40,000 |
$1,101 |
$0 |
$0 |
$0 |
|
$42,500 |
$1,545 |
$0 |
$0 |
$0 |
|
$45,000 |
$1,987 |
$355 |
$0 |
$0 |
|
$47,500 |
$2,429 |
$797 |
$0 |
$0 |
|
$50,000 |
$2,871 |
$1,239 |
$0 |
$0 |
|
$52,500 |
$3,313 |
$1,681 |
$0 |
$0 |
|
$55,000 |
$3,755 |
$2,122 |
$171 |
$0 |
|
$57,500 |
$4,197 |
$2,564 |
$613 |
$0 |
|
$60,000 |
$4,639 |
$3,006 |
$1,055 |
$0 |
|
$62,500 |
$5,095 |
$3,448 |
$1,497 |
$0 |
|
$65,000 |
$5,598 |
$3,890 |
$1,939 |
$95 |
|
$67,500 |
$6,100 |
$4,332 |
$2,381 |
$537 |
|
$70,000 |
$6,635 |
$4,774 |
$2,823 |
$979 |
|
$72,500 |
$7,217 |
$5,249 |
$3,625 |
$1,421 |
|
$75,000 |
$7,800 |
$5,751 |
$3,706 |
$1,863 |
|
$80,000 |
$9,123 |
$6,813 |
$4,590 |
$2,747 |
|
$85,000 |
$10,565 |
$7,978 |
$5,543 |
$3,631 |
|
$90,000 |
$12,111 |
$9,280 |
$6,527 |
$4,481 |
|
$95,000 |
$13,725 |
$10,550 |
$7,547 |
$5,293 |
|
$100,000 |
$15,378 |
$11,957 |
$8,656 |
$6,173 |
|
$105,000 |
$17,031 |
$13,544 |
$9,852 |
$7,157 |
|
$110,000 |
$18,685 |
$15,197 |
$11,223 |
$8,199 |
|
$115,000 |
$20,338 |
$16,850 |
$12,681 |
$9,395 |
|
$120,000 |
$21,991 |
$18,504 |
$14,335 |
$10,685 |
|
$125,000 |
$23,644 |
$20,157 |
$15,988 |
$12,092 |
|
$130,000 |
$25,269 |
$21,782 |
$17,613 |
$13,674 |
|
$135,000 |
$26,875 |
$23,388 |
$19,219 |
$15,280 |
|
$140,000 |
$28,481 |
$24,944 |
$20,825 |
$16,887 |
|
$145,000 |
$30,088 |
$26,600 |
$22,431 |
$18,493 |
|
$150,000 |
$31,694 |
$28,206 |
$24,038 |
$20,099 |
|
$155,000 |
$33,300 |
$29,813 |
$25,644 |
$21,705 |
|
$160,000 |
$34,906 |
$31,419 |
$27,250 |
$23,311 |
|
$165,000 |
$36,513 |
$33,025 |
$28,856 |
$24,918 |
|
$170,000 |
$38,119 |
$34,631 |
$30,462 |
$26,524 |
|
$175,000 |
$39,725 |
$36,238 |
$32,069 |
$28,130 |
|
$180,000 |
$41,445 |
$37,957 |
$33,789 |
$29,850 |
|
$185,000 |
$43,197 |
$39,709 |
$35,541 |
$31,602 |
|
$190,000 |
$44,949 |
$41,461 |
$37,292 |
$33,354 |
|
$195,000 |
$46,701 |
$43,213 |
$39,044 |
$35,106 |
|
$200,000 |
$48,453 |
$44,965 |
$40,796 |
$36,858 |
|
$205,000 |
$50,183 |
$46,696 |
$42,527 |
$38,588 |
|
$210,000 |
$51,914 |
$48,427 |
$44,258 |
$40,319 |
|
$215,000 |
$53,645 |
$51,888 |
$45,989 |
$42,050 |
|
$220,000 |
$55,376 |
$51,898 |
$47,719 |
$43,781 |
|
$225,000 |
$56,953 |
$53,466 |
$49,297 |
$45,358 |
|
$230,000 |
$58,496 |
$55,009 |
$50,840 |
$46,901 |
|
$235,000 |
$60,039 |
$56,551 |
$52,382 |
$48,444 |
|
$240,000 |
$61,582 |
$58,094 |
$53,925 |
$49,987 |
|
$245,000 |
$63,124 |
$59,637 |
$55,468 |
$51,529 |
|
$250,000 |
$64,667 |
$61,180 |
$57,011 |
$53,072 |
|
$275,000 |
$72,369 |
$68,811 |
$64,712 |
$60,774 |
|
$300,000 |
$79,730 |
$76,243 |
$72,074 |
$68,135 |
|
Source: The College Investor |
||||
Student Aid Index Calculator
Now that you know some of the basics, check out this SAI Calculator to see how your personal situation compares. This SAI Calculator has been updated for the 2027 – 2028 FAFSA.
MyCollegeCorner has a great SAI Calculator that can provide a pretty accurate result in about 8 minutes of data entry. Check it out here:
What Is The Student Aid Index?
The Student Aid Index (SAI) is simply a number that represents the “financial need” you have to afford college. The lower the number, the more need you have (e.g. you cannot afford to pay much towards college).
Due to the confusing nature of the EFC, lawmakers have decided to make a change. However, the reality is that the change is mostly in name.
The basics of the formula that calculator the resulting number will remain the same. However, the FAFSA Simplification Act has brought a few updates to the formula that will change the way colleges calculate a student’s financial needs.
So, what’s new?
Streamlined FAFSA Form
A major change is a more streamlined FAFSA form. Instead of answering over 100 questions, the FAFSA is only a few dozen questions. This should save students and parents time when applying for financial aid.
Cost Of Attendance Changes
The Cost of Attendance (COA) is another important number when sorting through college costs. Here are some of the changes including in the new law:
- A student will not need to be attending school on at least a part-time basis to allow for a personal computer’s rental or purchase. The student can be enrolled at any time commitment for this allowance.
- Transportation allowances between home, school, and work are allowed. A college financial aid administrator will set the actual transportation allowance.
- A student will need to be enrolled at least half-time to receive an allowance for personal expenses.
- Room and board allowances must be split into separate allowances for housing and meals. Meal allowances must be based on three meals per day.
- Housing allowances for students living in college-owned or operated housing will be based on the greater of the average or median housing costs.
- Housing allowances cannot be set to zero for students living with their parents at home.
- An allowance for private student loan fees is no longer applicable.
- An allowance for loan fees on federal loans for students and parents will be mandatory, instead of at the discretion of a college.
Trending Article Right Now
2027-28 FAFSA Guide
- Learn how to complete the 2027-28 FAFSA step-by-step
- Video tutorial and comprehensive question guide
Multiple Students Will Be Treated Differently
In the past, families with multiple students attending college at the same time on at least a part-time basis received special treatment. The parent assessment was divided by the number of family members in college.
Also, independent students had their family contribution divided by the number of students attending college on a half-time basis.
The SAI will not be divided based on the number of students in college within a family. With that, middle and high-income families may miss out on previous opportunities to save.
New Pell Grant Eligibility
Eligibility for Pell Grants will be based on a multiple of the poverty line. Households may qualify with incomes between zero and 175% to 400% of the poverty line. Additionally, incarcerated students will be eligible for the Pell Grant.
Negative SAI Will Be Possible
If the student is eligible for the maximum federal Pell Grant, the Student Aid Index will be set to 0. But the financial aid formula can allow for an SAI to be below zero, as low as -$1,500. This can help colleges more accurately determine a student’s financial needs.
Related: What Does A Negative SAI Mean
Other Changes
The really big change, not shown in this chart, is the elimination of the sibling loophole.
Previously, the number of dependents in college had two impacts. It divided the parent contribution and it reduced the income protection allowance. Eliminating the former causes a decrease in financial need. Eliminating the latter causes a slight increase in financial need. The impact of the former is greater as income increases, so it mostly leads to less aid for middle and high income families with multiple children in college at the same time.
Another change that is overlooked is the elimination of the state and local tax allowance. In high tax states, this will cause a big decrease in financial need, to the tune of thousands of dollars difference in financial aid, especially for middle and high-income families.
Pell Grant Eligibility Formula
Also, the secondary Pell Grant eligibility formula (minimum Pell Grant at 225% of the poverty line, maximum Pell Grant at 175% of the poverty line) is not shown in this chart.
Here are the thresholds so that you can compare them to the SAI Chart above (the 2027 – 2028 FAFSA/SAI will use the 2025 Poverty Line).
|
Family Size |
2025 Poverty Line |
175% Poverty Line |
225% Poverty Line |
|---|---|---|---|
|
1 |
$15,650 |
$27,388 |
$35,213 |
|
2 |
$21,150 |
$37,013 |
$47,588 |
|
3 |
$26,650 |
$46,638 |
$59,963 |
|
4 |
$32,150 |
$56,263 |
$72,338 |
|
5 |
$37,650 |
$65,888 |
$84,713 |
|
6 |
$43,150 |
$75,513 |
$97,088 |
Key SAI Observations
There are a few changes that we can see from looking at the SAI Chart.
- The SAI figures are lower than the 2026–27 chart at nearly every income level. The income protection allowance rose about 3.8%, the assessment brackets moved up, and the 2025 tax year carries a larger standard deduction, so more income is shielded before the formula assesses it.
- Each additional child reduces SAI by roughly $3,500 to $4,200 at incomes above about $125,000. At $150,000 AGI, one dependent gives an SAI of $31,694; two dependents drops it to $28,206, a decrease of $3,488.
- Each additional $10,000 in parent income raises SAI by about $3,200 to $3,500 between $100,000 and $220,000. Below $100,000 the increase runs from about $1,800 to about $3,300 per $10,000 as the assessment rate climbs from 22% to 47%.
- The income threshold for a $0 SAI increases with family size. A family with one dependent has a $0 SAI up to roughly $34,000 of AGI. A family with four dependents has a $0 SAI up to roughly $64,000.
- The impact of additional income on SAI is greater at higher income levels. For a family with two dependents, a $10,000 increase from $60,000 to $70,000 raises the SAI by $1,768 (from $3,006 to $4,774). The same $10,000 increase from $90,000 to $100,000 raises the SAI by $2,677 (from $9,280 to $11,957).
- At an AGI of $120,000, the SAI for a family with one dependent is $21,991. For a family with two dependents, it is $18,504, a decrease of $3,487.
- Pell Grant thresholds are higher for 2027–28. A family of four hits the 175% poverty line at $56,262.50 and the 225% line at $72,337.50, up from $54,600 and $70,200 for 2026–27.
- At very high incomes, SAI rises at roughly 29% to 31% of additional income once the 32% and 35% federal brackets and the Social Security wage base come into play. For a family with two dependents, going from $275,000 to $300,000 raises SAI by $7,362 (from $68,881 to $76,243), about 29.4% of the added income.
Common SAI Questions
What is the Student Aid Index (SAI)?
The Student Aid Index (SAI) is a measure of your financial need when it comes to college financial aid. The lower the number, the more financial need you have. It also directly impacts your eligibility for a Pell Grant.
Can My SAI Be Negative?
Yes, a negative SAI demonstrates the highest financial need. The lowest SAI score is -$1,500. However, all values $0 to -$1,500 are treated equally.
Does SAI Replace EFC Completely?
Yes, the SAI completely replaced the EFC score in 2024.
More Stories:
What Colleges Secretly Look For In Students For Admission
College Application Checklist: Timeline And Printable Calendar
10 Biggest FAFSA Mistakes That Could Cost You Financial Aid
Editor: Robert Farrington
Reviewed by: Chris Muller
The post 2027 – 2028 Student Aid Index (SAI) Chart And Calculator appeared first on The College Investor.

