The demand for semiconductors used in artificial intelligence (AI) applications, especially data centers, isn’t slowing down, as evidenced by the quarterly results of multiple chip companies so far this earnings season.
Nvidia (NVDA -4.12%) and Broadcom (AVGO -3.92%) are the two leading players in the AI chip market, clocking impressive growth in their data center businesses, driven by strong demand for their AI chips. However, both semiconductor stocks have underperformed the broader market this year for various reasons.
Nvidia stock is down by more than 12% in 2026, as of this writing. Broadcom, on the other hand, has been flat this year. These readings aren’t impressive, considering that the PHLX Semiconductor Sector has appreciated 43% in 2026. But the good part is that both Nvidia and Broadcom are trading at attractive levels.
So, if you had to choose one of these two chip stocks right now, which one should it be? Let’s find out.
Image source: Getty Images.
Nvidia: Why investors may want to adopt a wait-and-watch approach
Nvidia pioneered the AI chip revolution with its graphics processing units (GPUs). The company is now entering a new era following the departure of co-founder and ex-CEO Jensen Huang. Investors are rightly concerned about Nvidia’s future, as Huang played an instrumental role in making it one of the most influential companies in the world.
NVDA & AVGO: Performance Comparison
Key Financial Metrics

NVDA – Nvidia
$156.14
–4.12% (–$6.71)

AVGO – Broadcom
$333.40
–3.92% (–$13.61)
Market Cap
$3.9T
52wk Range
$148.80 – $243.37
Gross Margin
74.67%
P/E Ratio
20.59
EPS (TTM)
$7.91
Dividend & Yield
$0.52 (0.32%)
Market Cap
$1.7T
52wk Range
$289.77 – $495.00
Gross Margin
66.54%
P/E Ratio
44.30
EPS (TTM)
$7.83
Dividend & Yield
$2.60 (0.75%)
NVDA – Nvidia
$156.14
–4.12% (–$6.71)
Market Cap
$3.9T
52wk Range
$148.80 – $243.37
Gross Margin
74.67%
P/E Ratio
20.59
EPS (TTM)
$7.91
Dividend & Yield
$0.52 (0.32%)
AVGO – Broadcom
$333.40
–3.92% (–$13.61)
Market Cap
$1.7T
52wk Range
$289.77 – $495.00
Gross Margin
66.54%
P/E Ratio
44.30
EPS (TTM)
$7.83
Dividend & Yield
$2.60 (0.75%)
Not surprisingly, Nvidia stock is falling out of favor among Wall Street firms. Analysts are downgrading the stock due to concerns about Nvidia’s workplace culture, while its deals in China are also being scrutinized. Nevertheless, Wall Street still notes that Nvidia remains incredibly attractive from a valuation standpoint.
It has a price-to-earnings ratio of just 20, while the forward earnings multiple of 10 is even more attractive. Those are incredibly attractive multiples for a company that reported a 120% year-over-year increase in non-GAAP earnings per share in the last reported quarter. Notably, Nvidia’s long-term earnings growth estimates remain intact despite the recent turmoil.
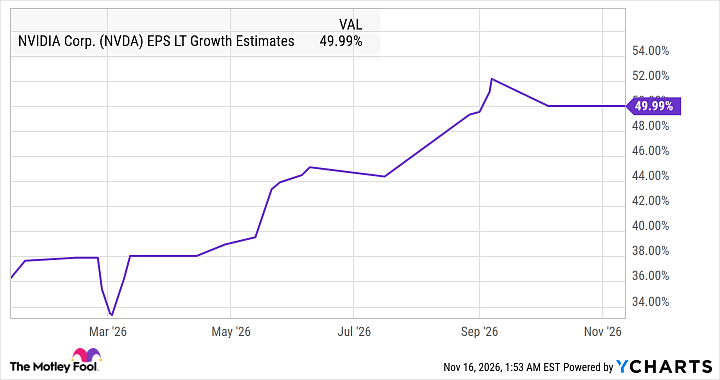
NVDA EPS LT Growth Estimates data by YCharts
However, cautious investors will do well to wait and see how the company’s fiscal Q3 earnings report, to be released on Nov. 17, turns out. A solid set of results, backed by impressive guidance, could improve investor confidence in the stock and spark a rally, suggesting that Nvidia’s growth trajectory is intact despite Huang’s exit.
But if Nvidia decides to pull its guidance in light of recent developments, the stock could fall further. So, it would make sense to hear what the company has to say on its upcoming earnings call before buying.
Broadcom: Time to buy the stock hand over fist
Broadcom has increasingly positioned itself as the next-most-important AI chip designer. This is evidenced by the exponential growth of its AI chip business, which is now outpacing Nvidia’s data center revenue growth.
Broadcom’s AI semiconductor revenue is estimated to have increased by 236% year over year in the fourth quarter of fiscal 2026 (which ended earlier this month) to $21.7 billion. That’s higher than the 221% year-over-year increase it reported in fiscal Q3. The company expects a 186% increase in AI chip revenue for fiscal 2026 to $58 billion. More importantly, it projects AI revenue will reach $230 billion in fiscal 2028.
This terrific growth explains why Broadcom’s earnings are expected to grow faster than Nvidia’s over the long run.
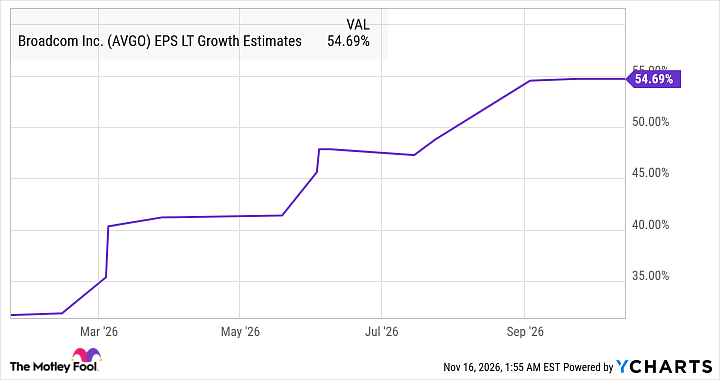
AVGO EPS LT Growth Estimates data by YCharts
Also, Broadcom can sustain its impressive growth beyond the next couple of years, driven by rising demand for custom AI processors and networking chips. The company reportedly controls 70% of the custom AI chip market, which is poised to clock a compound annual growth rate (CAGR) of 71% through 2030, according to a third-party estimate.
With Broadcom stock trading at an attractive 18 times forward earnings, which is lower than the tech-focused Nasdaq Composite index’s earnings multiple of 39, buying it seems like the right thing to do given its tremendous upside potential.
The following chart suggests that Broadcom’s earnings will grow significantly over the next couple of years from $11.66 per share in the recently concluded one.
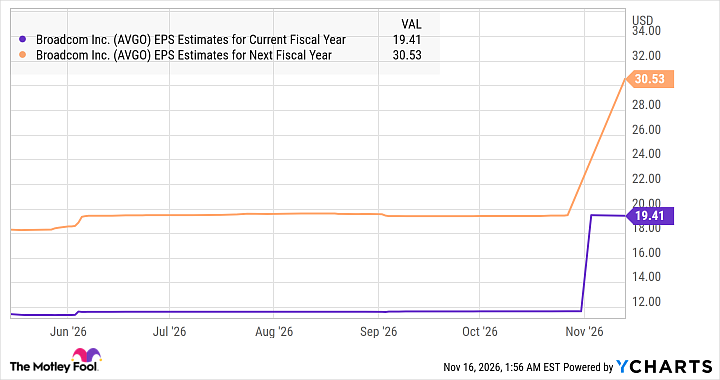
AVGO EPS Estimates for Current Fiscal Year data by YCharts
We have already seen that analysts anticipate Broadcom to clock long-term earnings growth of nearly 55%. Assuming its bottom line increases by even 25% in fiscal 2029, Broadcom’s earnings per share could reach $37.96 after three years. If the stock trades at even 30 times earnings, its price could reach $1,139.
That’s just over 3x Broadcom’s current price, which is why I think it may be a good idea to buy this stock hand over fist before it skyrockets.
Where to invest $1,000 right now
When our analyst team has a stock tip, it can pay to listen. After all, Stock Advisor’s total average return is 823%* — a market-crushing outperformance compared to 209% for the S&P 500.
They just revealed what they believe are the 10 best stocks for investors to buy right now, available when you join Stock Advisor.
See the stocks ›
*Stock Advisor returns as of November 16, 2026.

