
Why is iShares Russell 2000 ETF sliding today?
Home Blog
Why is iShares Russell 2000 ETF sliding today?
Mortgage Rates Hold Near 7.5% Despite Tech Stock Slide
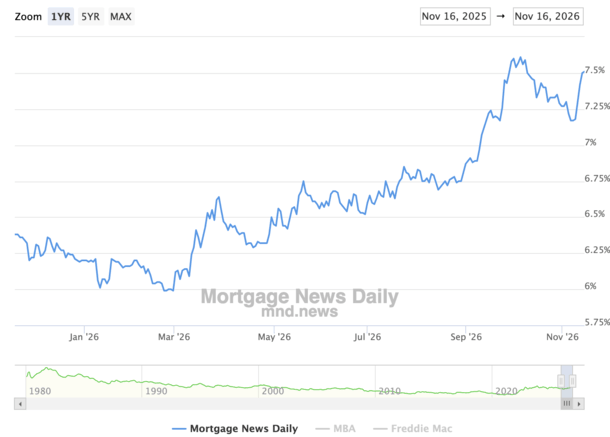
After one of the worst weeks for bonds in years, 30-year fixed mortgage rates are starting a fresh week stuck in the mid-7s.
The 10-year Treasury yield is down a couple ticks, but given the tech stock rout, it’s not offering up a whole lot of relief.
Typically bond yields (and mortgage rates) get help from stock market selloffs, but not so much today.
As such, mortgage rates are probably going to remain around 7.5% or so, and not far from their recent highs of 7.625%.
The question now is how do they get better if tech stocks are no longer helping?
Tech Stocks Are Under Pressure Again, But Mortgage Rates Aren’t Getting Much Help
At last glance, the tech-heavy Nasdaq was nearly 2% lower and the S&P 500 dropped more than 1%, with chip stocks the culprit.
The big story lately has been Nvidia and its embattled CEO Jensen Huang, who is now reportedly considering a return as CEO.
For the record, they report earnings tomorrow after the market close, which could play a major role for mortgage rates.
While the tech selloff didn’t help today, a bigger selloff linked to weak Nvidia earnings could potentially lead to another flight to safety in bonds.
If it does, mortgage rates would be the beneficiary, though the opposite also holds true.
If somehow Nvidia shakes off the recent CEO scandal and delivers hot earnings, we could see a risk-on move back into stocks and away from bonds.
That would result in even higher mortgage rates, which are already not far from recent highs.
The concerning part is Nvidia is already down like 35% from its recent highs and mortgage rates are still quite elevated, only about .125% below recent highs, per MND.
So you wonder how much a stock selloff can really help mortgage rates if it hasn’t done so already.
Fed Chair Warsh Talks AI as It Continues to Be Key Theme
Last week’s bond selloff was driven by economic data, and this week is full of Fed speakers.
This morning, Fed Chair Warsh spoke about AI, saying it could be huge or could be a dud.
One of the things he laid out before becoming the new Fed chair was supposed productivity gains from AI that would lead to disinflation.
Therefore, you could get lower interest rates while seeing economic growth and employment near full capacity.
But now he’s also saying it could “disappoint,” leading to a more near-term economic slowdown with job losses and perhaps a crashing stock market (something I definitely considered as did many others).
So again, AI is a key theme here whether it’s the Fed, the stock market, mortgage rates, or the wider economy.
All eyes seem to be on AI and whether it’s going to live up to its billing.
That’s probably the biggest driver of mortgage rates I’m looking at these days, aside from the major data reports like CPI, monthly jobs, etc.
[Compare mortgage rates and monthly payments side by side with my mortgage rate calculator.]
Oil and the Middle East Remain in the Background
While AI is the central theme of late, we still have elevated oil prices and tensions in the Middle East.
Things have been relatively quiet on that front, but it only takes one bad Iran headline to send oil (and inflation worries) right back up again, putting additional pressure on mortgage rates.
Given mortgage rates are already struggling despite the stock market carnage tells you the pressure is currently upward.
Tomorrow we get October retail sales, which economists expect to be a lot cooler than September’s 0.8% gain (just 0.2%).
If we happen to get a strong number, bond yields could continue to rise more above 5%, while making the case for a larger Fed rate hike next month.
The only real path to mortgage rate relief right now seems to be weak economic data and/or something majorly positive with Iran. Both don’t appear to be happening lately.
Read on: How are mortgage rates determined?
Before creating this site, I worked as an account executive for a wholesale mortgage lender in Los Angeles. My hands-on experience in the early 2000s inspired me to begin writing about mortgages 20 years ago to help prospective (and existing) home buyers better navigate the home loan process. Follow me on X for hot takes.
Latest posts by Colin Robertson (see all)
The Nvidia scandal fuels tougher China chip rules as Commerce targets Singapore and Malaysia
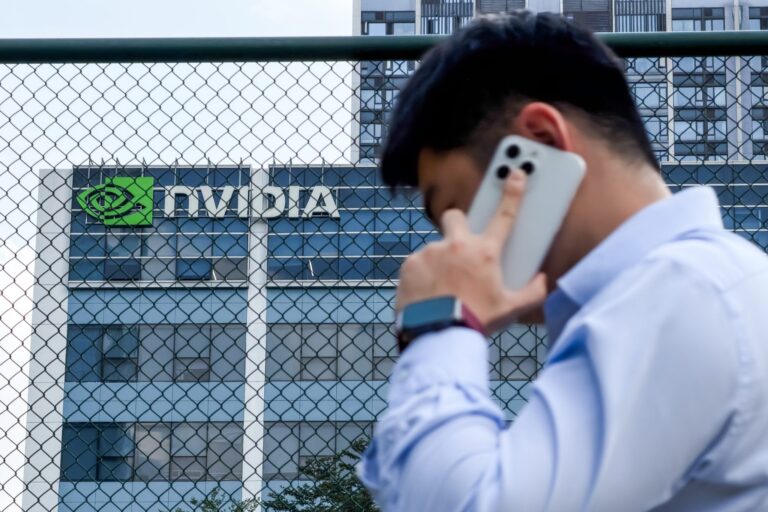
When Jensen Huang resigned as Nvidia’s CEO on Thursday, critics of the U.S.’s policy of restricting chip sales to China lost one of their biggest allies.
In addition to being one of the industry’s biggest proponents of the AI buildout, Huang remains one of the most vocal critics of U.S. policies that bar the sale of advanced chips and chipmaking equipment to China. He claimed that these measures would encourage the creation of a competing Chinese chip industry, and that it was better for the U.S. to keep Chinese companies hooked on U.S. technology.
Nvidia’s CEO was also a strong supporter of open-source AI models—many of which came from Chinese developers like DeepSeek—in the face of criticism that such models posed a serious cybersecurity threat.
Revelations that Huang had an affair with Alice Huang (no relation)—a former executive at Megaspeed, a Singaporean company suspected of funnelling controlled chips to China—has torched the Nvidia CEO’s credibility on the issue of export controls. (Some reports claim U.S. intelligence considered Alice Huang to be part of a Chinese espionage campaign against Nvidia, but others have cast doubt on that assessment).
On Monday morning, the U.S. Department of Commerce released the first update to its export control regime since the scandal broke, issuing an interim final rule that closes a longstanding loophole that allowed Chinese companies to access AI chips based in overseas data centers, and expands export controls to an array of Southeast Asian countries. Congress, too, is debating several laws that would codify and expand existing export controls.
Yet tighter rules may also complicate matters for other countries trying to forge a more neutral path between the U.S. and China
How likely are tighter export controls?
Current export controls block the most advanced AI processors—made by companies like Nvidia, AMD, and Intel—from being sold to Chinese companies, though the Trump administration has allowed sales of Nvidia’s H200 to approved Chinese customers. Chipmaking equipment and high-bandwidth memory are also blocked.
Commerce’s new rule—which will go into effect immediately once it’s included in the Federal Register—would require licenses to export advanced AI chips to data centers in Indonesia, Malaysia, Singapore, Thailand, and Brazil. It would also require a license if large data center operators anywhere in the world want to grant access to companies headquartered in China, effectively closing the remote access loophole. Data centers already serving such companies will have 90 days from the rule’s effective date to get a license.
The Trump administration may remain split on how to act against chip smuggling; interestingly, the press release from the Commerce Department notes the rules were “written by and at the direction of the Department of Treasury and the National Security Council.” But Congress may act if the Trump administration remains divided.
“The regulatory path in Washington is going to be harder and bumpier,” Hanna Dohmen, a senior research analyst at Georgetown’s Center for Security and Emerging Technology, told Fortune before the rule’s release. She pointed out that several bills have been included in this year’s National Defense Authorization Act. The Huang scandal “adds momentum to push those bills through, and the chance of those passing are likelier than ever.”
“No matter what Trump does, it’s possible that Congress should be able to provide limitations,” Joshua Kurlantzick, a senior fellow at the Council on Foreign Relations, said before the rule’s release. “It’s not only about Trump anymore.”
Congress, meanwhile, is closer than ever to locking those controls into law.
The first bill, the Remote Access Security Act, also seeks to close the remote access loophole, giving the Commerce Department authority to license and penalize foreign companies tapping advanced U.S. AI chips from abroad. (The House passed the bill in January and is still awaiting consideration in the Senate).
The second bill, the Chip Security Act, would require advanced chips to ship with security measures, like location tracking, to ensure processors aren’t diverted upon export. It also requires exporters to promptly disclose evidence of diversion or smuggling. Yet the act does not go as far as to mandate kill switches or more aggressive measures to stop smuggling.
The third, the AI Overwatch Act, would treat advanced chips like weapons: before any sale to China or other adversaries, the administration would have to notify Congress, which could then block the deal with a joint resolution of disapproval. It also carries an “America First AI” provision requiring Commerce to certify that exports won’t leave U.S. customers short of computing power.
The fourth, the MATCH Act, may be the most aggressive. The act would largely ban the sale and servicing of deep ultraviolet lithography tools across China, and imposes broader restrictions on facilities associated with major Chinese chipmakers like SMIC and CXMT. It gives allies like Japan and the Netherlands 150 days to align their own controls with Washington’s; if they fail, the U.S. can extend controls to equipment supplied from those countries, even if they contain no U.S.-made components.
Still, Dohmen pointed out that changing the rules alone won’t be enough to entirely halt chip smuggling. Several measures still require follow-on enforcement by either the U.S. or third parties; she pointed out that knowing that a chip was smuggled matters little if the Bureau of Industry and Security doesn’t act.
How might third parties respond?
Much of the attention during the Nvidia scandal has fallen on Southeast Asia, and Singapore and Malaysia in particular. Megaspeed, the company accused of funnelling Nvidia chips to China, is based in Singapore; Malaysia was also reportedly the home of Megaspeed’s data centers. Megaspeed has denied sending chips to China.
“The administration wants to encourage Malaysia and Singapore to remain in the American AI ecosystem, but it doesn’t want them to become conduits through which Chinese firms can obtain advanced chips—or remotely access the computing power those chips provide,” Jennifer Lind, associate professor of government at Dartmouth College, said. “That has been its policy so far and I don’t anticipate this changing.”
The new Commerce Department rule does offer a carve-out for end-users that are, or are owned by, a U.S.-headquartered company. The region has attracted billions of dollars of investment from U.S. tech companies such as Microsoft, Oracle, and Amazon, which should qualify for that exemption, though the rule’s remote access limits still apply to them.
While both Singapore and Malaysia have made some public moves against chip smuggling, Kurlantzick said he’s “more inclined” to believe the Singaporean government was taking the matter seriously. Malaysia, in contrast, “wasn’t really doing anything, and didn’t care,” he said. “The U.S. is insanely unpopular in Malaysia.”
Stopping Chinese companies from accessing chips in overseas data centers could be a problem for countries like Malaysia, which want to become data center hubs. “For Malaysia, the controls could be disastrous,” Kurlantzick said. “From what Prime Minister Anwar Ibrahim sees, their biggest potential future industry is a data center and AI hub for Chinese companies.”
The U.S. is also trying to draw countries into its “Pax Silica” framework, an initiative to secure semiconductor and critical mineral supply chains that bypass China. Beijing has a competing framework, the World Artificial Intelligence Cooperation Organization; the U.S. is pushing countries to choose one or the other. (Trump is in Manila this week for the ASEAN Summit, where he’s expected to persuade Southeast Asian countries to join Pax Silica—and perhaps now answer some awkward questions about these expanded rules.)
Still, Kurlantzick thinks the U.S.’s lack of attention to the region will hold back efforts to get other countries on board. “The U.S. isn’t really offering Southeast Asian countries–or really anyone in Asia–much in return for their demands,” he said.
Does China care anymore?
The biggest barrier to chips entering China right now isn’t Washington, but Beijing. The Chinese government has largely withheld permission for its companies to import Nvidia chips, instead pushing them to tap domestic chips made by companies like Huawei. DeepSeek in particular has led the drive to get Chinese AI models to run well on Huawei’s Ascend processors.
“Export controls still matter,” Lind said, though she admitted they may matter less now. “China is already well on its way toward developing its own AI ecosystem; Huawei makes its own chips for training and running AI models, and a software platform (CANN) that’s an alternative to Nvidia’s CUDA ecosystem,” she said.
She’s paying more attention to “whether semiconductor manufacturing equipment continues to be restricted—whether China develops the capability to manufacture its own frontier chips,” Lind said. “The Trump administration continues to restrict SME exports, and will likely continue to.”
Still, Huawei’s Ascend processors are not as good as the best Nvidia AI processors, particularly when it comes to training models.
Before the BIS announced its rule on Monday, Dohmen suggested that if Chinese companies can’t access Nvidia chips overseas, the roughly 600,000 H200s that Reuters reported are gathering dust in Hong Kong look more attractive.
“Would the Chinese government be more willing to let those H200s flow into China?” she asked. “If there is certain significant demand for remote access, and that’s cut off, there may actually be more need for the H200s.”
It’s not yet clear that China can supply all the computing power its AI developers need, particularly if overseas access disappears. China “does not have the capacity at this point to meet that demand,” Dohmen said.
🔴 LIVE 100$ Trading Challenge | Gold & Bitcoin Trading | Young Trader Viraj 🎉
🚀📈 WELCOME TO YTV 📈🚀
🔔 JOIN OUR FREE TELEGRAM CHANNEL 💬
📢 Get the latest market updates, trading insights, and important market developments.
👉 Telegram Channel:
🔗
━━━━━━━━━━━━━━━━━━━━━━
🤝 🚀 OUR TRADING PARTNERS 🚀
🔹 1️⃣ ELEFIN 📈
👉 Trade on Elefin:
🔗
🎟️ Partner Code: “ytv1”
🔹 2️⃣ XM 🌍📊
👉 Explore XM Trading:
🔗
🎟️ Partner Code: “YTV
🔹 3️⃣ DELTA EXCHANGE ⚡📉
👉 Create Your Account:
🔗
🔹 4️⃣ DHAN 📊💹
👉 Get Started with Dhan:
━━━━━━━━━━━━━━━━━━━━━━
🎓🔥 FREE EDUCATION & EXCLUSIVE ACCESS 🔥🎓
📚 FREE MASTERCLASS + VIP GROUP ACCESS 🎯
💡 Learn trading concepts, strategies, and risk management.
🤖 YTV EXCLUSIVE TELEGRAM BOT 🔐
🚀 Get access to exclusive community features!
👉 Join Here:
🔗
❤️📔 YTV AI JOURNAL 🤖📊
✨ Explore our AI-powered trading journal and improve your trading analysis.
👉 Visit Here:
🔗
━━━━━━━━━━━━━━━━━━━━━━
Live Gold Trading, Gold Trading Live, XAUUSD Live, XAUUSD Analysis, Gold Scalping Strategy, Gold Price Prediction, Live Forex Trading, Forex Trading Live, Forex Signals Live, Forex Market Analysis, Smart Money Concepts, SMC Trading, ICT Trading, ICT Concepts, Price Action Trading, Liquidity Trading, Market Structure Trading, Order Block Trading, Fair Value Gap Trading, FVG Trading, BOS Trading, CHOCH Trading, Institutional Trading, Intraday Trading, Day Trading, Scalping Trading, 1 Minute Scalping, 5 Minute Scalping, High Accuracy Trading, Professional Trading, Trading Psychology, Risk Management, Bitcoin Trading Live, BTCUSD Live Analysis, Crypto Trading Live, Cryptocurrency Trading, Nasdaq Live Trading, US30 Live Trading, Dow Jones Live, DXY Analysis, EURUSD Live, GBPUSD Live, USDJPY Live, Forex Education, Trading Education, Live Market Analysis, Real Time Trading, Trading Strategies, Beginner Trading Guide, Advanced Trading Strategies, Trading Community, Young Trader Viraj, YTV Live, YTV Trading, Trading Mentor, Stock Market Live, Financial Markets, Economic News Trading, CPI News Trading, NFP Trading, FOMC Trading, Breakout Trading, Reversal Trading, Trend Following Strategy, Support Resistance Trading, Liquidity Sweep Trading, Supply Demand Trading, Sniper Entry Trading, Trading Setups Live, Market Open Analysis, London Session Trading, New York Session Trading, Asian Session Trading.
#LiveTrading
#GoldTrading
#XAUUSD
#GoldLive
#ForexTrading
#ForexLive
#ForexSignals
#Scalping
#ScalpingStrategy
#PriceAction
#SMC
#ICT
#SmartMoneyConcepts
#Liquidity
#OrderBlock
#FairValueGap
#MarketStructure
#IntradayTrading
#DayTrading
#TradingLive
#TradingStrategy
#TradingEducation
#RiskManagement
#TradingPsychology
#BitcoinTrading
#BTCUSD
#CryptoTrading
#CryptoLive
#Nasdaq
#US30
#DowJones
#DXY
#EURUSD
#GBPUSD
#USDJPY
#MarketAnalysis
#LiveMarket
#TradingCommunity
#YoungTraderViraj
#YTV
#NFP
#CPI
#FOMC
#LondonSession
#NewYorkSession
#SupplyAndDemand
#SupportResistance
#BreakoutTrading
#ReversalTrading
#ForexIndia
live gold trading today
xauusd live analysis
gold trading strategy
live forex trading india
forex trading for beginners
bitcoin live trading
btcusd analysis today
smart money concepts live
ict mentorship concepts
1 minute scalping strategy
best forex trading strategy
live market analysis today
intraday trading live
day trading live stream
forex signals live analysis
gold price action trading
liquidity sweep strategy
institutional trading concepts
order block strategy
fair value gap strategy
GOLD Live Trading Session | XAUUSD Trading Live Stream |
LIVE FOREX ANALYSIS | LONDON STREAMS | GOLD & BITCOIN DAY 469 |
Live forex Trading | Live Trading
BITCOIN & GOLD LIVE TRADING ANALYSIS Live Trading || #goldtrading #cryptotrading
| Live Market Analysis for Gold and Crypto | US Session
Crypto Live Trading || #bitcoin #cryptotrading
BITCOIN LIVE TRADING ANALYSIS Live Trading || #goldtrading
“XAUUSD Gold Live Trading | London Session + New york Scalping & Forex Analysis”
Crypto Trading LIVE: BTC Live Trading and Bitcoin Analysis | #bitcoin
Gold Live Trading Session | XAU USD Analysis #btc #gold
Crypto Live Trading || l #bitcoin #cryptotrading
LIVE FOREX TRADING HINDI | NYC STREAM | GOLD AND BITCOIN TRADING |
GOLD Live Trading Today | XAUUSD Live Trading Session #397 |
Crypto Trading LIVE: BTC Live Trading Bitcoin Analysis | #bitcoin #btc
Live Crypto Trading | Bitcoin & Gold | | #goldtrading #cryptotrading #bitcoin
Live Crypto And Forex Analyisis and Trading | #livestream #crypto #bitcoin #forex #gold
“XAUUSD Gold Live Trading | London Session + New york Scalping & Forex Analysis”
🔴XAUUSD LIVE TRADING & Gold Signals – 24/7 Price Analysis & Trading Predictions
Live Intraday Trading | Crypto Bitcoin Live |
Live Crypto and Gold Scalping Trading || #goldtrading #bitcoin
source
Finding the Women
Responding to a letter to the editor, a Financial Analysts Journal co-editor draws on eight decades of data to examine women’s representation among the journal’s authors and editors and in finance industry leadership.
Best Bank Account Interest Rates for November 2026
Get the Real Story on Your Next Exec Hire
<p>What top leaders ask to elicit honest, actionable insights about executive hires.</p>
Supreme Court of Canada dismisses bid to appeal B.C. foreign buyer tax case

The Supreme Court of Canada won’t hear an appeal challenging the application of British Columbia’s foreign buyer tax on a real estate purchase involving joint ownership by a Canadian citizen and a foreign national.
CME vs. Morningstar: Which Financial Stock Is a Better Buy for 2027?

When choosing between exchange operators and data providers, do you prioritize massive profit margins or broad research influence? CME Group (CME +0.78%) and Morningstar (MORN +0.07%) offer two distinct paths for investors.
CME Group provides the plumbing for global derivatives trading, while Morningstar serves as a trusted voice in investment research. Both companies benefit from the long-term growth of the financial markets, yet they operate with very different business models and capital structures. This comparison evaluates their financial health and risks to determine which is better for 2027.
The case for CME
CME Group operates a global marketplace for derivatives, allowing participants to trade futures and options across major asset classes. As a leader among financial stocks, it partners with Alphabet (GOOGL -0.98%) (GOOG -0.96%) for technology infrastructure and Flutter Entertainment (FLUT -1.02%) for prediction market applications. One clearing firm accounted for nearly 12% of clearing and transaction fees in 2025, and customer concentration like this adds a layer of risk to the business.
In the 12 months ended Sept. 30, 2026, revenue reached nearly $7 billion, representing approximately 9% growth over the previous 12-month period. The company reported net income of roughly $4.4 billion, resulting in a robust net margin of nearly 63.1%. This performance follows a consistent upward trend in revenue and earnings, driven by increased trading activity across its diverse global exchange platforms.
As of CME’s December 2025 balance sheet, the debt-to-equity ratio, a metric that compares total debt to shareholder equity to assess financial leverage, is 0.1. The current ratio, which indicates its ability to cover short-term debts with its current assets, reached 1. In the fiscal year ended Dec. 31, 2025, free cash flow was nearly $4.2 billion, representing the cash generated after accounting for capital expenditures to maintain operations.
The case for Morningstar
Morningstar provides essential investment research and financial data to eight primary customer groups, including wealth managers, asset managers, and individual investors. The company operates more than 40 offices globally, offering critical solutions for retirement plan providers, institutional asset owners, and fixed-income security issuers. No single customer accounted for more than 3% of its revenue in 2025, which reflects a highly diversified and resilient client base.
In the 12 months ended Sept. 30, 2026, revenue was nearly $2.6 billion, representing growth of roughly 9.4% over the prior 12-month period. The company generated net income of approximately $445.5 million, supported by rising demand for its data products and research tools. This growth highlights the steady expansion of its footprint in the financial data industry as advisors and investors seek deeper market insights.
As of Morningstar’s December 2025 balance sheet, the debt-to-equity ratio is 1.2. The current ratio is 1. In the fiscal year ended Dec. 31, 2025, free cash flow was close to $442.6 million.
CME & MORN: Performance Comparison
CME – CME Group
$317.97
+0.78% (+$2.47)

MORN – Morningstar
$246.26
+0.07% (+$0.18)
Key Financial Metrics

CME – CME Group
$317.97
+0.78% (+$2.47)
MORN – Morningstar
$246.26
+0.07% (+$0.18)
Market Cap
$114B
52wk Range
$218.31 – $322.82
Gross Margin
82.76%
P/E Ratio
26.07
EPS (TTM)
$12.20
Dividend & Yield
$5.15 (1.61%)
Market Cap
$9.1B
52wk Range
$141.49 – $251.04
Gross Margin
55.23%
P/E Ratio
21.53
EPS (TTM)
$11.44
Dividend & Yield
$2.00 (0.81%)
CME – CME Group
$317.97
+0.78% (+$2.47)
Market Cap
$114B
52wk Range
$218.31 – $322.82
Gross Margin
82.76%
P/E Ratio
26.07
EPS (TTM)
$12.20
Dividend & Yield
$5.15 (1.61%)
MORN – Morningstar
$246.26
+0.07% (+$0.18)
Market Cap
$9.1B
52wk Range
$141.49 – $251.04
Gross Margin
55.23%
P/E Ratio
21.53
EPS (TTM)
$11.44
Dividend & Yield
$2.00 (0.81%)
Risk profile comparison
CME Group faces risks from fluctuating trading volumes, which are sensitive to global economic conditions and market volatility. Intense competition exists from traditional exchanges and alternative trading venues like Intercontinental Exchange (ICE +0.36%) and Cboe Global Markets (CBOE +1.77%). The company must also navigate significant regulatory compliance costs and potential legislative changes that could impact its global exchange operations.
Morningstar is subject to risks from economic downturns, which can negatively affect its asset-based revenue when market values decline. It faces fierce competition from large data providers such as MSCI (MSCI +1.34%) and S&P Global (SPGI +1.08%), as well as the risk of product obsolescence due to new technologies like artificial intelligence. Any errors in its research or ratings could lead to reputational damage or potential legal liability for the firm.
Valuation comparison
Morningstar currently trades at lower multiples relative to its sales and future earnings estimates, making it appear more reasonably priced than the premium-valued CME Group. The forward P/E ratio compares a stock price to future earnings estimates, while the P/S ratio measures the price against sales over the past 12 months.
| Metric | CME Group | Morningstar |
|---|---|---|
| Forward P/E | 25.4 | 18.8 |
| P/S ratio | 16.2 | 3.5 |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
Which stock would I buy for 2027?
Both Morningstar and CME Group posted similar revenue growth for the (roughly) trailing-12-month period, so there’s not much to separate them there. However, CME has a robust net margin, clocking in at over 60%. Morningstar isn’t even close; the company’s net margin is about 17%.
Another thing I find appealing about CME is that it pays a modest dividend yielding about 1.6%. Morningstar’s yield is only 0.8%.
That said, let’s turn to the tape:
CME data by YCharts
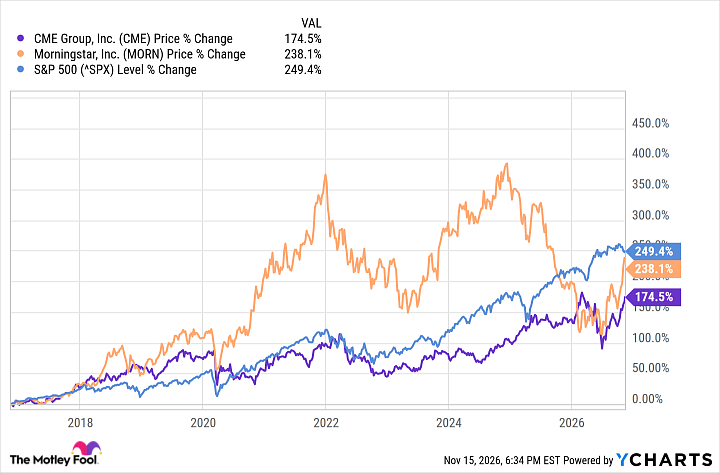
Over the past decade, Morningstar shares have outperformed CME Group by more than 60 percentage points. But neither kept pace with the S&P 500, which is not a good look. Past performance is no indication of future results, of course. But it would be frustrating to be a shareholder of either company during that time frame and not see even average returns.
The final thing I’ll note about Morningstar in the chart above is that the stock experienced considerably more volatility than CME Group. If you’re an investor who’s especially sensitive to that, Morningstar may not be the right choice.
I own shares of CME and don’t intend to sell them anytime soon. CME gets my vote for 2027, but perhaps it’s worth considering a simple ETF that follows the S&P 500.
Where to invest $1,000 right now
When our analyst team has a stock tip, it can pay to listen. After all, Stock Advisor’s total average return is 823%* — a market-crushing outperformance compared to 209% for the S&P 500.
They just revealed what they believe are the 10 best stocks for investors to buy right now, available when you join Stock Advisor.
See the stocks ›
*Stock Advisor returns as of November 16, 2026.
Introduction to Management, chapter 1, part 1 Management: An Overview
Introduction to Management, chapter 1, part 1 Management: An Overview
learn the following topics in this part;
Define Management
Explain the Significance of Management
List Managerial Functions
#khanacademy
#khanacademyeducation
#valuetainment
#harvardbusinessreview
#exam
source