
Since prediction markets exploded in popularity in 2024, the industry’s two leading players, Kalshi and Polymarket, have been raising staggering amounts of money. In the case of Kalshi, the startup notched a $1 billion Series F in May that valued it at $22 billion, and investors are eyeing an initial public offering as soon as next year. But even as the company pulls in gobs of revenue, its business model faces huge uncertainty due to a looming Supreme Court case that raises the question of whether that valuation is justified. Now, research firm PitchBook has put out a 46-page report that seeks to define Kalshi’s true worth.
The detailed report by analyst Franco Granda parses financial metrics and examines the legal landscape confronting prediction markets, and ultimately concludes Kalshi should be valued at $30.4 billion based on expected 2028 adjusted earnings. The report qualifies that figure by forecasting that assigns a $22.8 billion valuation to the company in the event of a bear case scenario, and a $42.1 billion figure for a bullish scenario.
As the following graphic shows, PitchBook predicts Kalshi’s revenue will reach $6.4 billion by 2030, and that the company will pull in $3.7 billion in adjusted earnings:
In an interview with Fortune, Granda shared his view that the company is an enviable competitive position since its main rival, Polymarket, has been able to overcome the early lead Kalshi built among U.S. consumers thanks to a more cautious revenue strategy. Granda added that Polymarket is also spending considerably more on promotions to acquire new customers, and the prediction market industry has become effectively a two-horse race that will see a handful of other players fighting for scraps.
“Third parties will pick up crumbs here and there but the window of opportunity for people to get in has passed,” said Granda. The report, meanwhile, included a graph showing the respective volume for the two industry leaders:
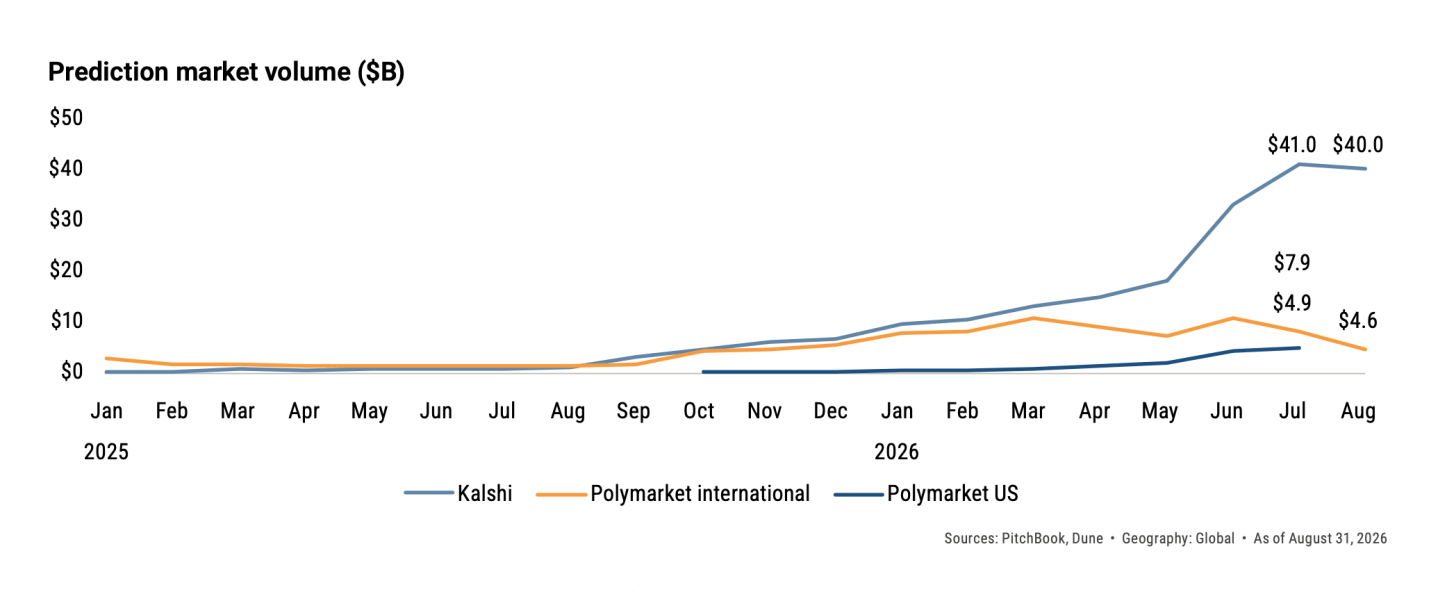
The PitchBook report further predicts that Kalshi will be able to consolidate its lead on the strength of partnerships with distribution platforms like Robinhood, market makers like Susquehanna, and numerous other tie-ups.
Since Kalshi is a private company that is not obliged to publish its financials, PitchBook’s predictions are based in some cases on estimates rather than hard figures. According to the company, its report contract draws on data from Kalshi’s API, PitchBook’s internal data, Dune databases, government filings, management commentary, and public peers’ disclosures.
And while the PitchBook offers a broadly bullish outlook for Kalshi, that calculation is based on a reading of the legal tea leaves that some may view as optimistic.
The Supreme Court wildcard
Prediction markets differ from traditional sports books in that customers don’t bet against the “house” but against anyone willing to take the other side of a yes/no contract. This distinction means sites like Kalshi are typically more profitable than regular betting sites since they are not at risk of losing money in the case of an unexpected outcome.
This business advantage offers one explanation for why prediction market startups have become so valuable. But, for now, they also enjoy what may be an even bigger advantage: a different regulatory regime that allows the likes of Kalshi and Polymarket to pay fewer taxes and court younger customers.
Unlike conventional sports books, which operate on the basis of licenses issued by states, Kalshi and Polymarket argue they are exclusively regulated at a federal level by the Commodity Futures Trading Commission. This has allowed them to offer their products to customers as young as 18, versus 21 for sports books, and also to avoid paying state taxes.
The problem for Kalshi and others is that their legal case is strong when it comes to prediction markets related to elections, entertainment and so on—but is weaker when it comes to sports. That has led states and Indian tribes to sue Kalshi on grounds that it is allegedly offering unlicensed sports gambling.
This is a major concern for investors since, as PitchBook notes: “The sports dispute threatens Kalshi’s main source of fees, with the category accounting for 69.9% of event fees YTD, rising to 82.4% when including exotics.” (In this context, “exotics” describes parlays and other multi-leg forms of betting that require a user to correctly guess the outcome of multiple different games.)
The issue of whether or not Kalshi and Polymarket’s sports offerings are legal is being hotly litigated in dozens of states and, so far, courts are for the most part ruling against the company. Contradictory rulings from two appeals courts, the 3rd Circuit and the 9th Circuit, have teed up a so-called circuit split and made the case ripe for the Supreme Court, which is widely expected to hear it next year.
While PitchBook acknowledges that an adverse legal ruling at the Supreme Court would be a blow, the report concludes that it would not be existential, noting that “For illustration, a 25% reduction in sports and exotics gross fees would remove $642 million from our 2026 forecast and $1.4 billion from 2030.”
In Granda’s view, Kalshi would be able to quickly adapt in the event the Supreme Court rules against the company, in part by adopting a state licensing model. That view may be sanguine, according to legal experts, however, who told Fortune that the company has angered many state law-makers and that it would be hard-pressed to reconstruct its business model.
A final consideration informing Kalshi’s future valuation is how quickly the company can build out wagers that are not related to sports. The most promising of these is perpetual futures, according to PitchBook, which forecasts net transaction revenue of $50.7 million in 2026, and $275.7 million in 2030—healthy figures but hardly enough to meaningfully offset a total loss of sports-related revenue.
You can read the full Pitchbook report, titled “Kalshi Initiation Report: A prediction market for anything, but its own future” here.

